


TLDR
- Public companies holding large cryptocurrency positions are currently trading at market caps well below the value of the tokens they actually hold (in some cases at 50 cents on the dollar or less). That gap is a NAV (Net Asset Value) discount, and can create a strategic entry point for allocators.
- Institutional allocators who understand closed-end fund mechanics will recognize this pattern immediately. The gap between market price and asset value is the entry point, and history suggests it can close quickly.
- Treasury strategies built on the Avalanche token ($AVAX) are uniquely suited to capitalize on this dynamic, with a capped supply, institutional adoption, and emerging use cases that make it a quality asset to hold over time.
CRYPTO TREASURY STRATEGIES + THE CLOSED-END FUND PARALLEL
In closed-end funds, a fund holds a fixed pool of assets (bonds, equities, real estate, etc). Shares in the fund trade on an exchange. Those shares have a market price. That price tracks the underlying asset value but isn’t anchored to it: factors like sentiment, liquidity, and investor demand can create a gap above or below NAV.¹
The result is a persistent phenomenon that institutional allocators are familiar with: the discount to NAV.²,³ The fund holds $100 in assets. The shares trade at $85. The gap is the discount.
A crypto treasury strategy behaves the same way. The company serves as an institutional gateway to a crypto ecosystem by holding a portfolio of digital assets (typically, a token). Meanwhile, its stock trades on a public exchange. Its mNAV (the ratio of market cap to underlying asset value) is rooted in fundamentals but can fluctuate based on market sentiment.
An mNAV of 1.0 means the stock is fairly valued against its holdings. An mNAV of 0.75 means you’re buying $1.00 of digital assets for $0.75 through the stock. An mNAV above 1.0 (which some companies that are employing similar treasury strategies have traded at during peak enthusiasm) means the market is pricing in a premium for the access and structure the company provides.
In the current market, many companies employing treasury strategies trade below 1.0. As of early 2026, even the most established treasury company in the market (Michael Saylor’s Strategy) was trading at or below the value of its holdings.⁴
The question is why these companies are trading at a discount, and whether that can change.
WHY THE DISCOUNT FORMS
Three major factors, among others, contribute to the discount.
- Institutional infrastructure is nascent. Accounting standards for digital assets have advanced, and regulatory frameworks are taking shape. But crypto treasury strategy companies are still ahead of the tooling built around them. Outside of the largest names, dedicated analyst coverage of the category as a structure is thin. There’s no standard index tracking it. And many investment policy statements that now permit digital asset exposure still don’t have explicit language covering equity wrappers around token treasuries. That limits the pool of eligible buyers, and constrained demand shows up as a discount.
- The liquidity premium problem. Holding the token directly is more straightforward than holding equity in a company that holds the token. The company adds overhead, management risk, and corporate structure. Investors are starting to price that friction into the stock.
- Operational drag. Most of these treasury companies are early-stage, and their overhead can exceed operating revenue in the near term. The market discounts the treasury asset by the expected cost of running the company over time, sometimes more aggressively than the actual numbers justify. Treasury companies with relatively low operating expenses are therefore likely to be more attractive to institutional investors.
The question isn’t whether the discount closes completely, but whether it closes enough to matter. And historically, the gap between where these discounts start and where they stabilize is where the return is.
WHAT HISTORY SUGGESTS
The most relevant precedent for treasury companies is closed-end fund discount research. Work on this going back to the 1980s shows a consistent pattern: when closed-end funds trade at significant discounts to NAV, mean reversion follows.³ Sometimes it’s triggered by shareholder pressure to restructure the fund. Sometimes it’s simply market recognition that the gap has gotten too wide.
The gap doesn’t stay wide indefinitely, in either direction. Discounts compress as the structure matures and institutional frameworks catch up, bolstering fundamentals. As digital assets move from speculative exposure to recognized balance sheet items, which is happening across major financial institutions, the discount should compress.
History shows evidence for this compression. We saw a version of this with REITs in the early 1990s: new structure, thin institutional understanding, meaningful discounts. As the framework matured, those discounts compressed and the asset class re-rated substantially.
THE STAKING YIELD CHANGES THE MATH
The historical evidence is already strong, but staking provides an additional benefit for crypto treasury strategies when compared to closed-end funds.
A closed-end fund holding bonds or equities has a mostly static asset base. While the market waits for the discount to close, the NAV moves with the underlying market but doesn’t compound independently of it.
A treasury holding staked tokens is different. The underlying asset generates yield in the form of additional tokens, simply by being deployed in the network. Validators earn staking rewards. Delegation fees add incremental revenue. The NAV grows not just with token price, but with token accumulation.
What this means practically: a crypto treasury trading at a 50% discount to NAV isn’t just a bet on the discount closing. It’s a bet on the discount closing while the underlying NAV is simultaneously growing from staking rewards. The two sources of return compound in parallel.
Example: AVAX One
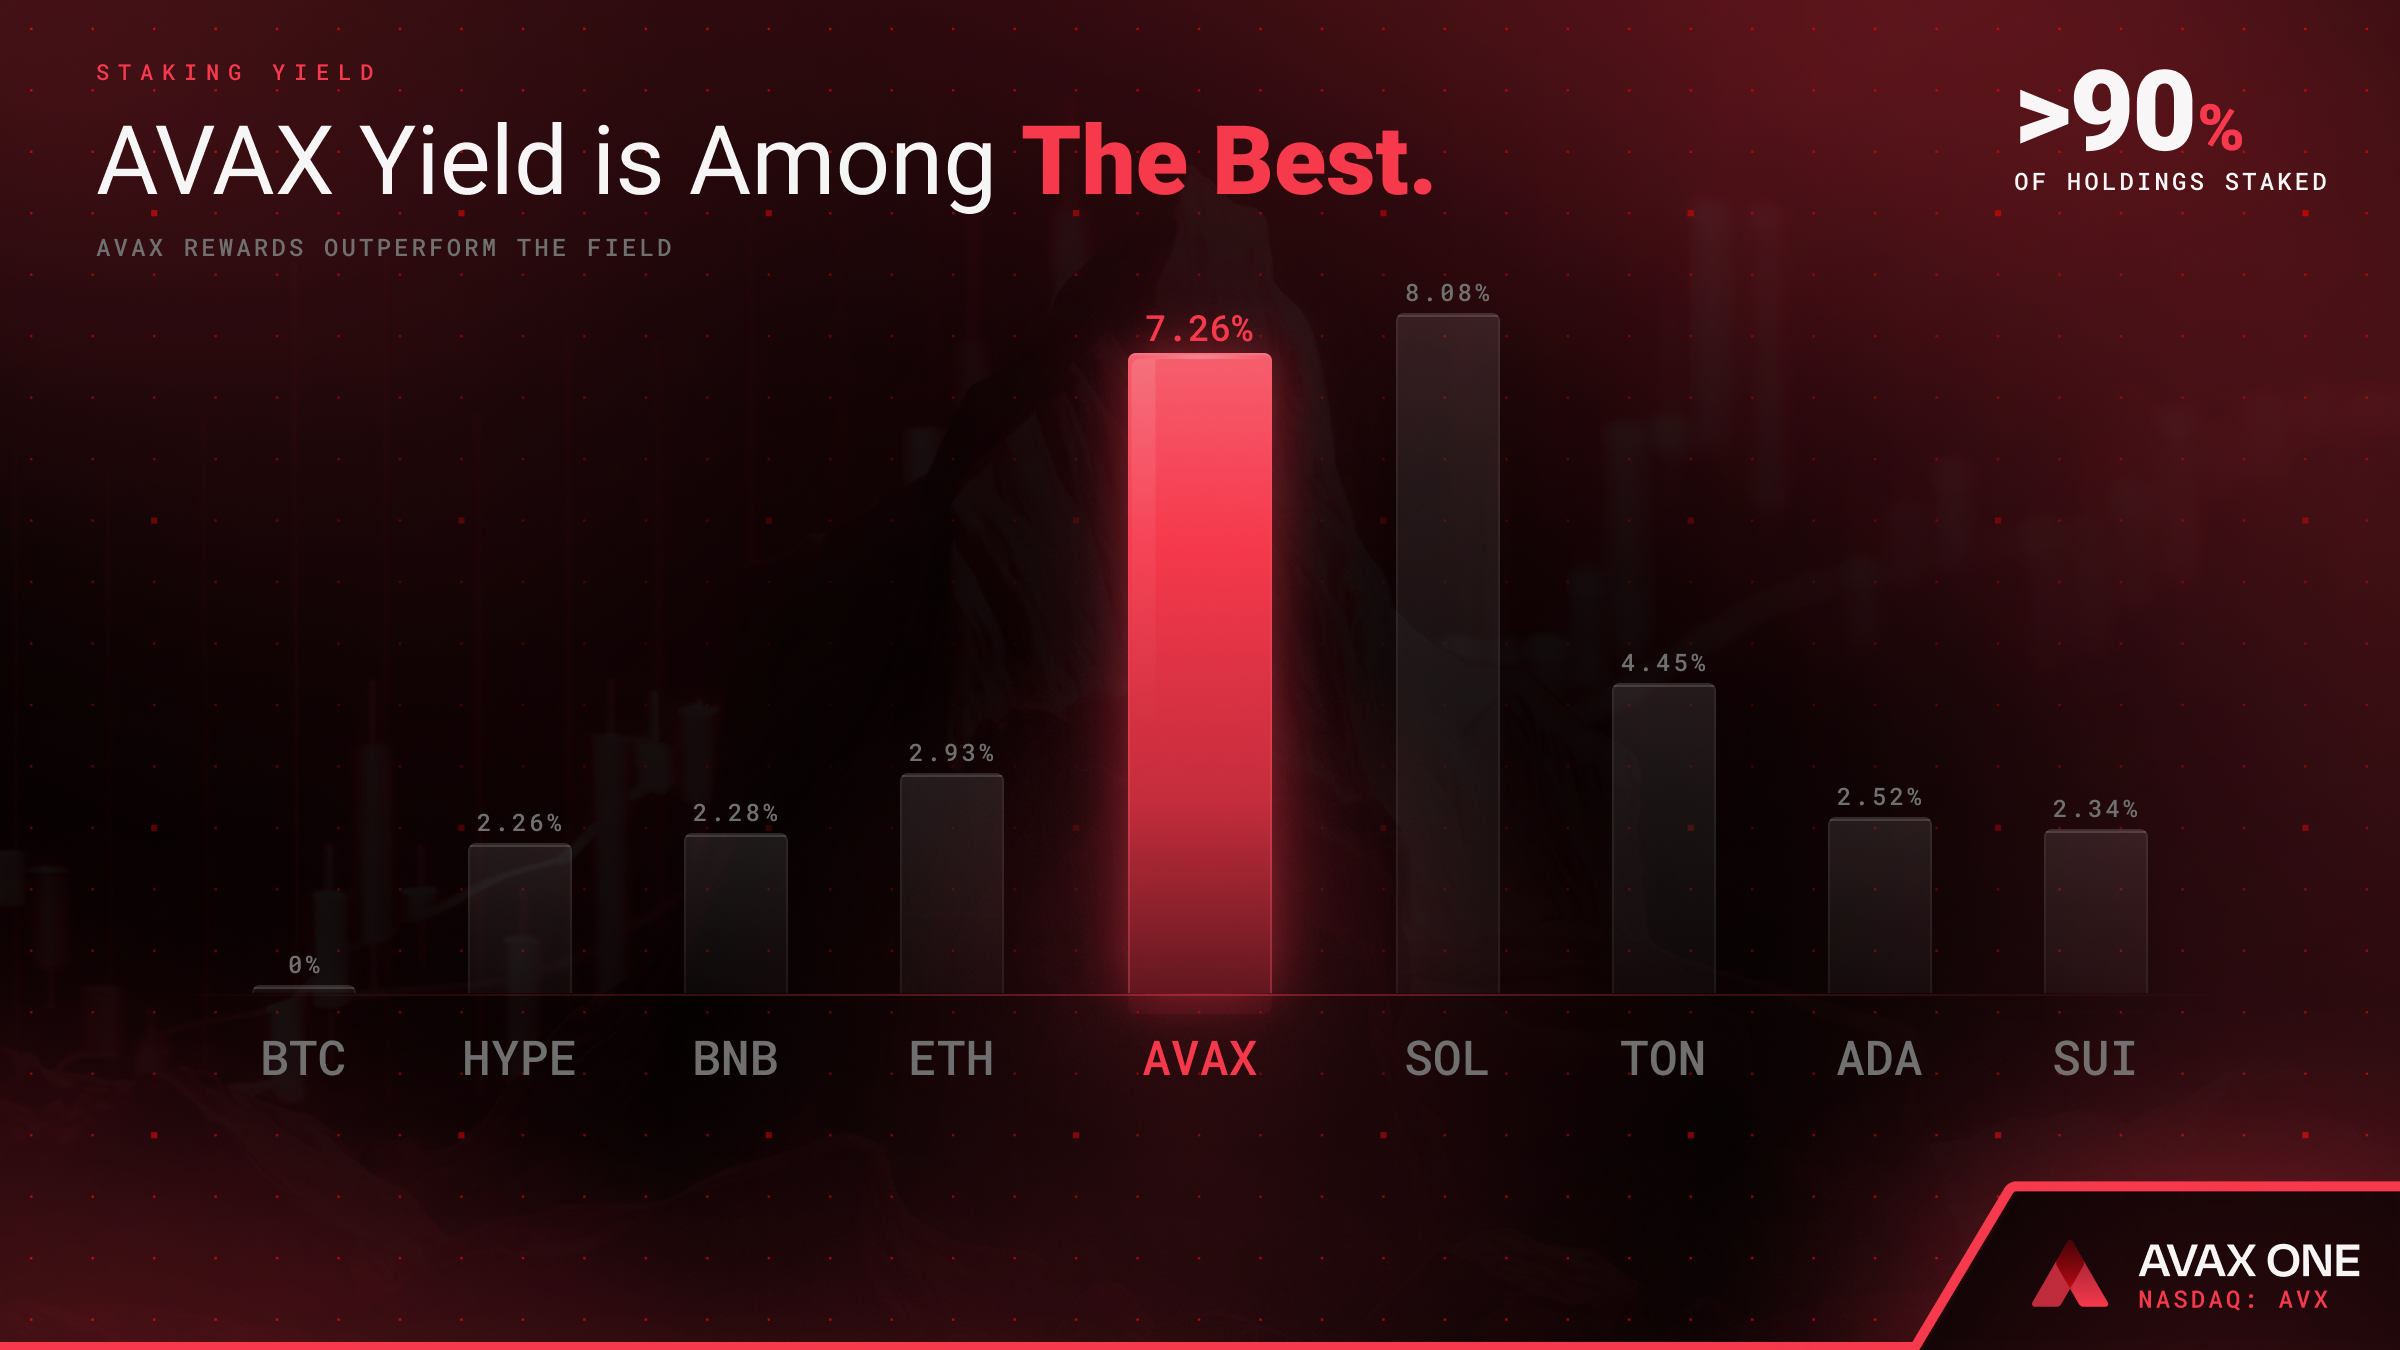
AVAX One is currently staking more than 90% of its AVAX holdings, and generated approximately $600,000 net yield from staking rewards in December. It is forecasting similar monthly returns for Q1 2026, anticipating 180,000 AVAX in staking rewards (approximately $1.7 million in value at today’s prices).
WHY AVAX FITS THE TREASURY STRATEGY MODEL
The quality of the underlying token in a treasury can also have a significant impact, just as the quality of assets in a closed-end fund matters.
Avalanche checks the boxes that institutional allocators care about.
- Supply is capped and long-term deflationary. AVAX has a hard maximum of 720 million tokens.⁶ There is no path to unlimited dilution. And unlike protocols that pay transaction fees out to validators, Avalanche burns its fees, removing tokens from circulation permanently. Every transaction on the network, at scale, tightens supply.⁶,⁷ That matters for a treasury strategy because accumulation compounds differently when supply is contracting. Every AVAX token added to the treasury represents a growing share of a shrinking float: the network’s own activity works in the same direction as the accumulation strategy.
- The yield is structural. AVAX staking rewards are built directly into the protocol. Validators earn rewards based on uptime and responsiveness.⁶ Assuming sustained network activity, it compounds with the holdings. The protocol also rewards long-duration commitment: validators who stake for longer periods earn meaningfully more than those staking for the minimum term (and those rewards are significantly greater on AVAX than on other chains, as seen in the chart below).
- Real institutional adoption is already underway. Global institutions including KKR, Apollo, and JPMorgan have used Avalanche’s infrastructure to explore tokenizing real-world assets.⁸,⁹ That adoption is what drives sustained network activity, and network activity is what drives fee volume, validator rewards, and ultimately the value of the underlying token.
The practical result: a treasury strategy built on AVAX holds an asset with a fixed supply that’s actively being reduced by fee burning, generates compounding yield from a protocol mechanism that isn’t going away, and sits underneath a network with documented institutional demand and an expanding set of real-world use cases.¹⁰
AN ENTRY FRAMEWORK
The mNAV ratio gives allocators a simple, legible way to think about relative value across companies employing crypto treasury strategies.
A company trading at 0.50x mNAV holds $100 in digital assets for every $50 in market cap. If that discount compresses to 1.0x (without any change in the underlying token price) the equity position has doubled.
This is not a guaranteed outcome. Token prices are volatile. Operational costs are real. But regulatory treatment of digital assets is evolving, with meaningful legislative frameworks advancing in the U.S., from the passage of the GENIUS Act in July 2025 to continued consideration of the Clarity Act in 2026.
Those discount mechanics, historical precedents, and the improving regulatory backdrop together make the mNAV a framework worth tracking for allocators looking for a more capital-efficient entry.
A SHORT WINDOW FOR MISPRICING
Markets misprice what they have difficulty measuring, and crypto treasury strategy companies are at the early stage of that cycle right now. Institutional coverage is thin. Accounting standards for digital assets are still being finalized. Most investment policy statements haven’t been updated to include treasuries as an explicit category.
Even Strategy has, at times, been suspect to this discount, suggesting the entire category, not just smaller names, is caught in this mispricing window. This is also the environment where discounts are widest: where the asymmetry is largest for allocators who can build a framework before the rest of the market does.
And by the time these companies have a clean accounting category, a standard index, and three years of analyst consensus estimates, the discount will have already compressed.
REFERENCES
- Fidelity. “Closed-End Fund (CEF) Discounts and Premiums.” Fidelity Learning Center. https://www.fidelity.com/learning-center/investment-products/closed-end-funds/discounts-and-premiums
- Dimson, E. and Mussavian, M. “The Closed-End Fund Discount.” AIMR, December 2002. https://www.cefadvisors.com/Download/200212-AIMR-Discount.pdf
- CAIA Association. “What We Like About Closed-End Funds.” CAIA Alternative Investment Analyst Review, Q2 2012. https://caia.org/sites/default/files/5what_we_like_about_closedend_funds_caia_aiar_q2_2012.pdf
- Bitcointreasuries.net. “Strategy.” Feb. 2025 https://bitcointreasuries.net/public-companies/strategy
- Avax One. “AVAX One Provides Strategic Update on AVAX Treasury and Ongoing Growth Initiatives.” January 28, 2026. https://ir.avax-one.com/news/?qmodStoryID=6223677709487876
- Buttolph, S., Moin, A., Sekniqi, K., and Sirer, E.G. “Avalanche Native Token ($AVAX) Dynamics.” Ava Labs, June 2020. https://www.avalabs.org/whitepapers
- Avalanche Support. “Tokenomics FAQ.” Avalanche Support Center. https://support.avax.network/en/articles/6912428-tokenomics-faq
- The Block. “JPMorgan, WisdomTree team up with Avalanche, Axelar, LayerZero on blockchain interoperability.” November 15, 2023. https://www.theblock.co/post/263109/jpmorgan-apollo-axelar-oasis-pro-provenance-blockchain-interoperability
- TechCrunch. “Avalanche Foundation to invest $50M in asset tokenization on its blockchain.” July 25, 2023. https://techcrunch.com/2023/07/25/avalanche-foundation-to-invest-50m-in-asset-tokenization-on-its-blockchain/
- Grayscale Research. “Building Block: Avalanche.” 2024. https://research.grayscale.com/token-fundamentals/building-block-avalanche


